// FIRST LIGHT Good morning. Voters handed Democrats control of Congress overnight. They won both chambers and take over in January. The bond market reacted like a lender that expects fewer new loans. It bought. Gold jumped. Stocks sold hard first, then changed their minds before dawn. Today brings the government's borrowing plan and a survey of the services economy. Both test whether the bond market's reading of the vote holds up. Our call is below. 
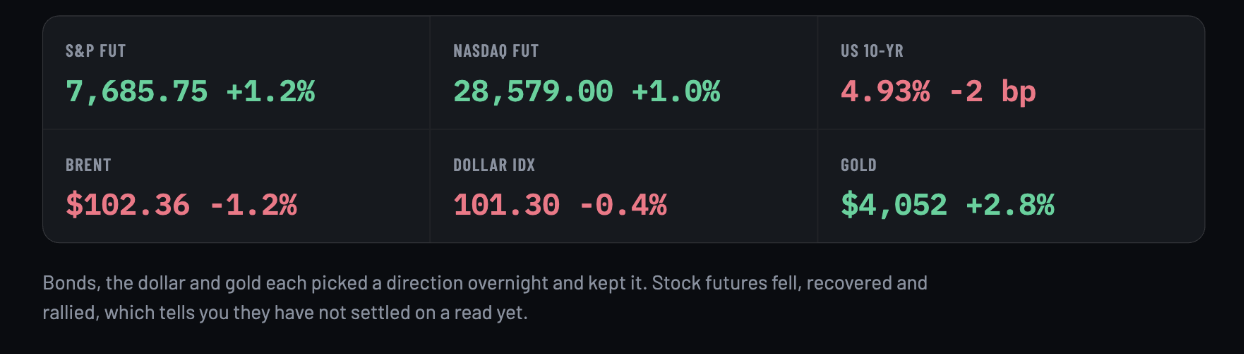
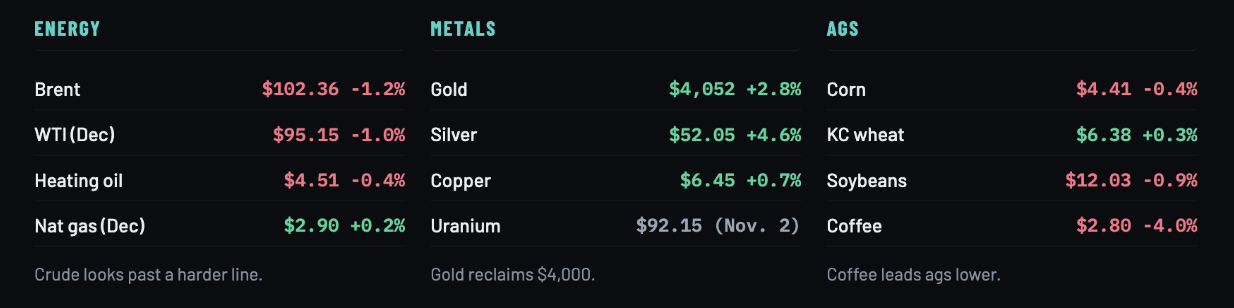
// THE SETUP Bonds appear to read a Democratic Congress as a brake on borrowing. Stocks have not decided Democrats won control of both chambers on Tuesday. The AP called the Senate shortly before midnight, and Democrats flipped at least seven Republican-held seats without losing any of their own. Several races are still being counted. Prediction markets had priced Democratic Senate control between about 73 and 77 cents on Election Day, so the outcome was favored but not fully priced. Treasuries rallied, the dollar weakened and gold cleared $4,000 overnight, while stock futures erased their early losses. The 10-year yield was near 4.93%, about 2 basis points below Tuesday's close. Gold futures rose about 2.8%. Nasdaq 100 futures fell more than 2% at their low, then turned higher. S&P futures were up about 1.2% before the open. The likeliest bond reading is about supply. A Congress run by the other party makes large new tax cuts, spending programs and tariff bills less likely. Fewer new deficits would mean less new Treasury debt, so investors could demand a smaller premium for holding long bonds. A weaker dollar fits that reading. So does gold, which gains from both a softer dollar and demand for protection. There is a plainer reading, too. Some buyers wanted shelter while stock futures were falling. The dollar's drop looks American, not European. The euro rose about 0.6% even as France's services sector shrank at its fastest pace since May. One market disagrees with bonds outright. Kalshi's contract on a December Fed rate hike rose to 78 cents from 74 cents, even as two-year yields slipped. What would change the read comes quickly. Treasury's quarterly refunding statement before the open sets the supply of longer bonds for the months ahead. The ISM services index follows mid-morning, with forecasts calling for 54.8. A hot print would challenge the bond rally from the growth side. Friday brings October payrolls. > SAVANTS SIGNAL The call is that bonds keep the brake reading through the close. Expect the 10-year yield to close below Tuesday's 4.95% on the Cboe measure, after both the refunding and the ISM report. Expect the dollar index to stay below Tuesday's 101.74. Position for duration over the dollar while both hold. PREMIER FEATURE The SpaceX IPO made Elon Musk the wealthiest man who has ever lived. Now he's spending it to complete his dynasty... He's already acquired a $40 billion AI firm and a $1 billion turbine company. But a handful of companies still stand between him and total control of the space economy. 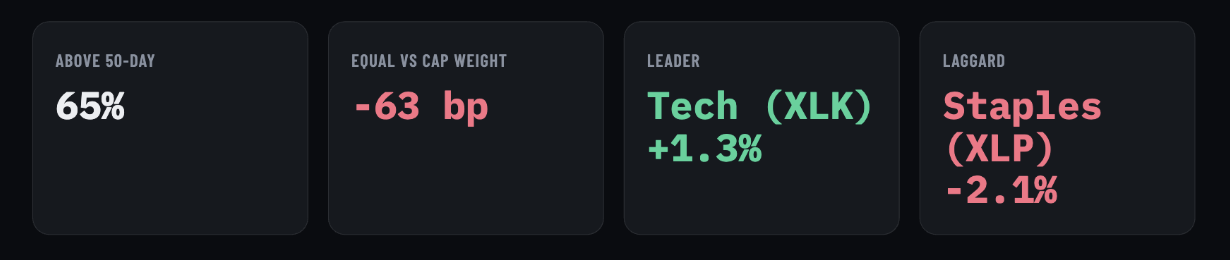 Tuesday's gain was narrow. The S&P 500 rose 0.4%, yet only 191 of its 503 members rose by our count. The Invesco S&P 500 Equal Weight ETF (RSP) fell 0.3%. Chips carried the index, with the iShares Semiconductor ETF (SOXX) up 2.5%, while consumer staples sold off. This morning the sorting looks political. First Solar (FSLR) was indicated about 8% higher and Enphase Energy (ENPH) about 6%. Lockheed Martin (LMT) was about 3% lower and Tesla (TSLA) about 4.5% lower. The group worth your attention is AI, which split in two. The suppliers that just reported rose. Arista Networks grew revenue 58.5% on AI networking, and Arista (ANET) was about 11% higher. Super Micro's revenue nearly quadrupled to $19.9 billion, and Super Micro Computer (SMCI) gained about 8%. Skyworks Solutions (SWKS), still tied mostly to smartphones, was about 15% lower after a weaker outlook. The companies that rent out AI computing went the other way. CoreWeave (CRWV) and IREN (IREN) were each about 3.5% lower, though Nebius (NBIS) was little changed. These landlords sit where tighter oversight and costlier borrowing meet. IREN reports Thursday and CoreWeave on Nov. 10. Crypto took the same round trip as stock futures. Bitcoin fell to about $75,700 overnight and recovered to near $78,600. Coinbase (COIN) was about 2% higher. The industry's market-structure bill now faces a Congress run by Democrats. > SAVANTS SIGNAL The vote appears to sort stocks by policy exposure rather than lift them evenly. The cleanest split is inside AI, between suppliers with orders in hand and landlords that need cheap financing. Treat that gap as the market's view on who pays for the build-out. > SAVANTS SIGNAL A ratio that rises on gold says the night's move was a hedge, not relief for fuel buyers. Gold miners such as Newmont (NEM), up about 5.5% premarket, sit in that path. A settle above 39 with gold above $4,000 means the hedge held. // FRONTIER DESK The signal. Meta Platforms sold $15 billion of bonds at yields of 5.85% to 7.53%. Orders reached about $58 billion, Bloomberg reported, close to four times the deal. The longest bond priced about 0.9 percentage point wider than a comparable Meta Platforms (META) bond sold in April. So what. Demand for AI debt held, but its price rose. Higher borrowing costs raise the return each new data center must earn. The money still lands at the chipmakers. AMD guided to about $17 billion of quarterly revenue, well above forecasts, while its free cash flow fell 64%. Inventories rose about $3 billion in three months. Private lenders keep raising money, too. Blackstone (BX) said it has closed about €13 billion of investable capital for European direct lending, including anticipated leverage. Tuesday's Apple tell ended undecided, with the stock closing at $331.90, between our $325 and $338.32 lines. Frontier watch. Three things not yet priced. Meta's first euro-denominated bond sale, which could come as soon as today. Results after the close from Qualcomm (QCOM) and Arm Holdings (ARM). And reports from IREN on Thursday and CoreWeave on Nov. 10, early reads on AI landlords after this week's bond sales. The tell. Advanced Micro Devices (AMD) against $483.90 and $517. A close above $517, near where it traded overnight, means investors are paying for growth despite thin cash conversion. Below Tuesday's $483.90, the cash flow statement won. Between them, the market is undecided. Exposed. META, AMD, CRWV, IREN, NBIS, BX // POSITION CHECK Forget forecasts. Tell us what you did with bonds or gold after the vote. Added | Held | Trimmed | Not my market PARTNER SPOTLIGHT The Closest Thing to a Virtual AI Monopoly Wall Street Is Ignoring
A little-known company is building what may be the closest thing to a virtual monopoly the AI era has ever seen. Only 3... Yet it beat Apple, Amazon, and the S&P 500 combined... While paying out $146,000 in total dividends on a 1,000-share stake. Kevin O'Leary calls what it controls a "unicorn." Right now, it's trading at a rare discount. This ad is sent on behalf of Stansberry Research, 1125 N Charles St, Baltimore, MD 21201. If you would like to optout from receiving offers from Stansberry Research please click here. // ON DECK When (ET) | What | | | Before the open | ADP private payrolls, then Treasury's refunding statement. Watch any change to its guidance on coupon sizes | | | Mid-morning | ISM services index, forecast 54.8. A hot reading would test the bond rally | | | Late morning | Government crude inventories, after the industry's 5.27 million barrel draw | | | Close | The 10-year against 4.95% and the dollar index against 101.74 grade the call. AMD's close resolves the tell | | | After close | Qualcomm, Arm, AppLovin and Coherent report | |
|
|
That is the setup. We will tell you this afternoon whether it held. Market Savants | Stocks, macro, commodities, AI Forward this to the person who thinks an election only moves stocks. |