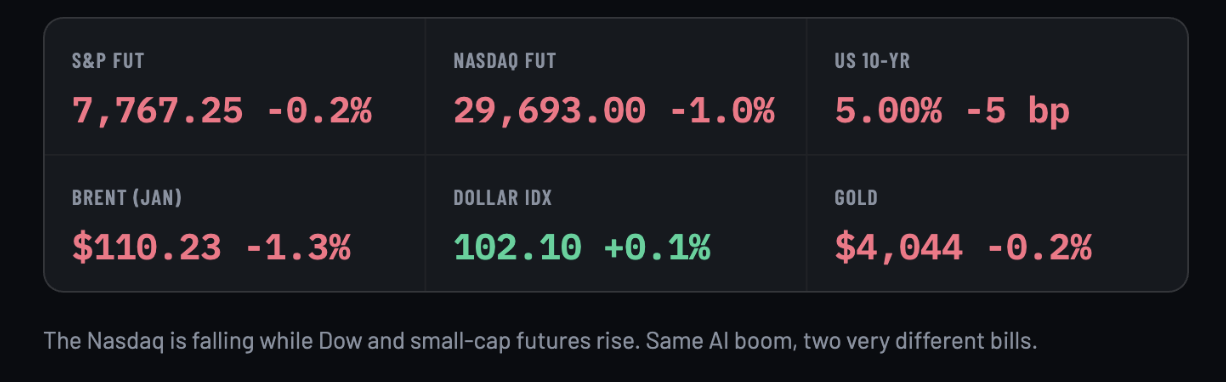
// FIRST LIGHT Good morning. For two years, a bigger AI budget was the good news. Investors bought the spender and every supplier behind it. Last night two of the biggest spenders came in under forecast, and the market split them anyway. It rewarded the one paying from its own pocket. It marked down the one raising outside money to keep up. That is a new kind of question for this cycle, and this morning's GDP report puts the same question to the economy. Our call is below. 
// THE SETUP Investors appear to be pricing AI by who pays for it, not by how much gets spent Alphabet and Microsoft both spent less on AI last quarter than analysts expected. Alphabet's capital spending was $51.4 billion against about $55.1 billion forecast. Microsoft's was $45.2 billion against $50.7 billion. Both were still far above a year ago, up 114% and about 30%. The stocks went opposite ways. Alphabet (GOOGL) was indicated near $291 early Thursday, about 10% below Wednesday's $324.89. Microsoft (MSFT) was indicated near $545, up about 3%. Nasdaq futures fell while Dow and Russell futures rose. The difference is the cash line. Alphabet's free cash flow was negative $9.1 billion, its second straight negative quarter, and it raised about $41 billion of debt and new stock to cover it. Free cash flow is the cash left after paying for equipment and buildings. Microsoft said some third-party data-center deliveries were delayed and guided above $50 billion this quarter. It also trimmed its 2026 outlook to about $170 billion from about $175 billion, citing the same delays. Wednesday pointed the same way. Oracle (ORCL) rose 10.6% as it capped new outside capital at $20 billion through fiscal 2030 and dated its return to positive free cash flow. Its revenue target was no surprise. The funding limit was. The second-order cost lands in bonds. Alphabet's long-term debt reached $125.1 billion at the end of September, up from $46.5 billion at the end of 2025. Borrowing on that scale adds long-dated supply that investors must absorb beside Treasury issuance. The 10-year closed Wednesday near 5.04% after the Fed held, then eased to about 5.00% overnight. What would change the read is a market that sells every AI name alike, or one that forgives Alphabet by the close. This morning's GDP report is the macro test. The Fed chair expects business investment to lead it, and forecasts call for growth near 3%. Prediction markets put the odds of a December hike near 83% on Wednesday. > SAVANTS SIGNAL The call is that the market keeps sorting AI by funding through the close. Expect Alphabet to finish at least 7% below Wednesday, under $302.15. Expect Microsoft to close above Wednesday's $531.01. Expect the equal-weight S&P 500 (RSP) to beat the Nasdaq 100 (QQQ) on the day. Position for a market that prices AI spenders by balance sheet. PREMIER FEATURE 7 Income Machines Built to Make You RichThe 7 Stocks to Buy and Hold Forever aren’t just plays for the next quarter - they’re built to deliver for decades. These are blue-chip companies with fortress balance sheets, elite dividend track records, and the staying power to outperform in bull and bear markets alike. Some are Dividend Kings, others are on the path there, and all are proven wealth compounding machines. // UNDER THE INDEX 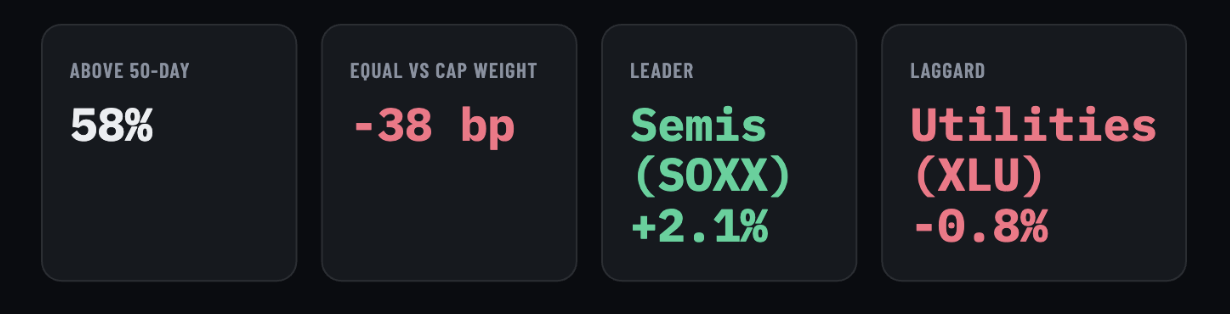 Wednesday's 0.3% gain in the S&P 500 was narrow. By our count, 249 of 503 members rose. Chips led it. Overnight that leadership reversed, and crypto moved with tech, not the Fed. Bitcoin slipped below $80,000 overnight as tech futures slid, despite a third straight day of ETF inflows, and hovered near it early Thursday. Coinbase (COIN) and Strategy (MSTR) report tonight.
The group worth your attention is AI's suppliers, because their revenue is the hyperscalers' spending. KLA (KLAC) guided revenue about 5% above forecasts and was indicated about 3% higher. Micron, AMD and Broadcom were each indicated roughly 2.5% to 3% lower. If Microsoft is right that deliveries were late, most supplier orders shift in time rather than vanish. Its lower 2026 figure says not all of them land this year. Software fared worse. ServiceNow (NOW) was indicated 18% lower despite guiding to faster subscription growth, and Fortinet (FTNT) 26% lower after raising its billings forecast. > SAVANTS SIGNAL Supplier stocks are trading the spenders' headlines, while KLA's guidance still points up. Amazon's capital spending tonight is the next dated test. Read the funding line before the spending line. // THE BARREL 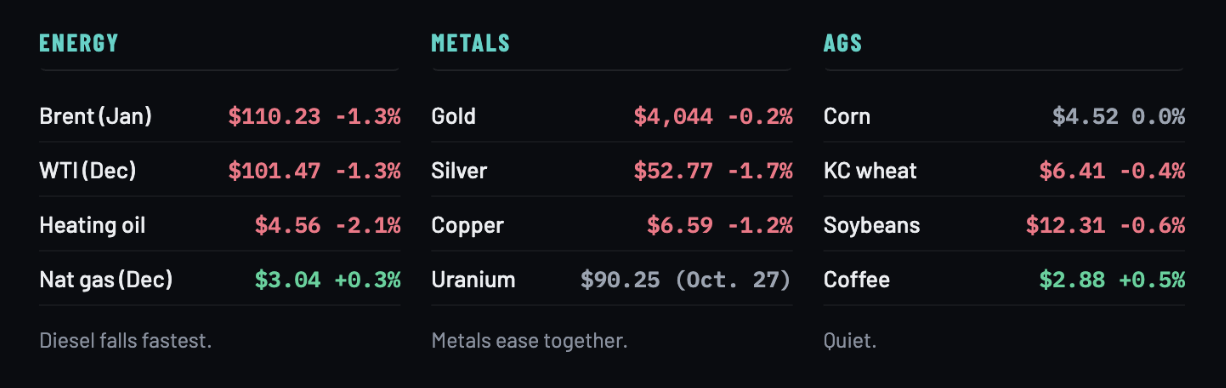 Spread of the day. The diesel crack, heating oil against January Brent in dollars per barrel, was about $81.50 this morning. That is roughly $2.80 narrower than Wednesday's settles. Heating oil fell faster than crude, which may point to product supply rather than only a fading war premium. Oil slipped after reports of a Vance letter to Tehran, and JPMorgan analysts said Russian refinery runs rebounded by 350,000 barrels a day last week. The same night, the Associated Press reported allies were told to prepare for possible U.S. strikes after the Nov. 3 midterms. Polymarket's ceasefire contracts imply more strike risk in the week ending Nov. 15 than in the next 10 days combined. Shell and TotalEnergies, meanwhile, are handing the windfall back through buybacks.
> SAVANTS SIGNAL A narrowing crack is relief for diesel users, from freight carriers and airlines to farms. A settle below $82 would suggest refinery supply, not only diplomacy, is easing the squeeze. A rebound above $84 would put the strike calendar back in charge. FROM OUR PARTNERS 
Renowned tech investor James Altucher – the man who called the rise of Nvidia, Apple and SpaceX years in advance – just uncovered Elon Musk’s latest breakthrough idea…And according to James, it’s going to be even bigger than the SpaceX IPO – creating up to 1.8 million new millionaires over the coming years. The pieces behind it are inside this briefcase – which he reveals 100% FREE in this video. // FRONTIER DESK The signal. Marvell Technology is reported to be in advanced talks to buy Lumentum, which was worth about $83 billion at Wednesday's close. Bloomberg and Reuters reported the talks, citing people familiar. No agreement has been announced. Marvell (MRVL) was indicated about 11% lower and Lumentum (LITE) about 6% higher. So what. It is the Setup's question at the component level. Lumentum's lasers move data between AI chips, and Nvidia (NVDA) has paid to secure supply. Marvell's cash would cover less than 5% of the target, and Bernstein told Reuters a deal would likely need more financing. The early verdict suggests investors are charging the buyer for dilution. Private money keeps flowing elsewhere. FuriosaAI raised $620 million at about $2.9 billion, and a Korean state fund put in about $280 million, about 45% of the round, Bloomberg reported. TPG is in talks to buy Elliott's UK data-center business for about $5 billion, the Financial Times reported, though talks could still fail. Frontier watch. Three things not yet priced. Amazon's capital spending and cloud growth tonight. Whether Alphabet draws on the $27.6 billion left in its stock-sale program. Terms of any Marvell deal, especially the mix of cash and stock. The tell. Marvell's close. Below $226.50, the market is rejecting a deal it expects to be paid for largely in stock. Above $240, it shrugged. Between them, it is undecided. Exposed. MRVL, LITE, NVDA, AMZN, ORCL, CRWV // POSITION CHECK Forget forecasts. What did you do with megacap tech this month? Added | Held | Trimmed | Not my market PARTNER SPOTLIGHT He predicted the 2008 financial crisis…He predicted Trump’s election in 2016…. He even predicted the rise of COVID-19 writing: “The chance we don’t have something on the scale of a national pandemic in the next few years is near zero” That was three months before the first reported case. If he’s right again, God Bless America… Because this crisis will be tectonic in scale…and it's going to begin with the bubble popping in AI. // ON DECK Time ET | What | | | 08:30 | Q3 GDP, September PCE and jobless claims. How much of growth is business investment? Core PCE against a 0.3% monthly forecast | | | 09:15 | ECB decision, press conference at 09:45 | | | 13:00 | $44 billion seven-year note sale. Demand for duration after the Fed | | | 14:30 | Brent settles; December expires Friday. Diesel crack above or below $82 | | | 16:00 | Alphabet, Microsoft, RSP and QQQ grade the call. Marvell's close grades the Frontier tell | | | After close | Amazon, Intel, Coinbase and Strategy report | |
|
|
That is the setup. We will tell you this afternoon whether it held. Market Savants | Stocks, macro, commodities, AI Forward this to the friend who still thinks a bigger AI budget is always good news. |